9 Apr 2022
530

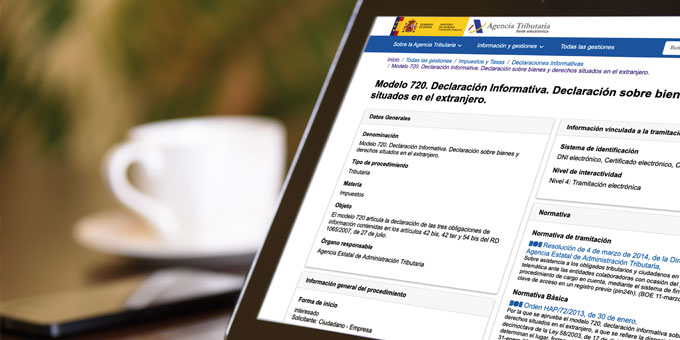
With Law 5/2022, which was published in the Official Gazette ("BOIB") on 10 March, 2022, the legislature has adapted the controversial tax form 720 to European law. About 10 years ago, the form ("modelo") 720 was introduced in Spain with the aim of forcing Spanish tax residents to disclose assets located abroad. Since then, all tax residents have been called upon to report information about their accounts with foreign banks, shares of stock and real estate assets. However, this only applied if the value of one of these three asset classes exceeded 50,000 euros.
Failure to submit this declaration on time, or to file incorrect information, has resulted in significant penalties: There were fixed fines ranging from 100 to 5,000 euros for incorrect information, and in the worst cases there were further fines of up to 150% of the tax liability. In some cases this meant that the taxes to be paid were higher than the value of the assets which were not declared. From the beginning, the tax form 720 - with its catalogue of fines and no statute of limitations on tax liability - was very controversial in Spain and at EU level.
The Court of Justice of the European Union (CJEU) ruled at the end of January 2022, that some of the obligations contained in this form are in breach of European laws. The ruling said that the fines for taxpayers as stated in the sanction regulations of Form 720, are excessive and violate the principle of the free movement of capital. In addition, failure to report assets results in undeclared income being taxed as unjustified capital gains, without the taxpayer being able to invoke the four year statute of limitations otherwise applicable in Spain. Finally, the CJEU states that the amount of the fines imposed is disproportionate to the sanctions generally provided for by the laws of Spain for similar infringements.
Tax form 720 has now been amended by Law 5/2022 in two key points: 1) The disproportionately high fines are eliminated. The previous sanction regulations, which provided for fixed fines for each violation and a penalty of up to 150%, are replaced by the regulations of the General Tax Code.2) The 720 tax model is now subject to the statute of limitations of general tax law, which means that any tax debts become barred by statute after four years. However, it should be noted that the duty of tax residents to report foreign assets abroad has been retained. The CJEU did not question the obligation to submit Form 720. The tax return for the previous year must be submitted by the end of March of the following year at the latest.
According to some tax advisors, a taxpayer who did not previously declare foreign assets due to the high fines, can do this now after the change of law. They need to file tax form 720 for the four previous years in addition to the current year. Since the CJEU ruling, taxpayers have been able to reclaim part of the fines that were un awfully paid in the past. If administrative proceedings are still ongoing, the fines can be challenged with reference to the CJEU ruling and taxes can be reclaimed if they are barred by the statute of limitations. With regard to proceedings that have already been completed, taxpayers can assert a claim for repayment via state liability ("responsabilidad patrimonial del estadolegislador").
Failure to submit this declaration on time, or to file incorrect information, has resulted in significant penalties: There were fixed fines ranging from 100 to 5,000 euros for incorrect information, and in the worst cases there were further fines of up to 150% of the tax liability. In some cases this meant that the taxes to be paid were higher than the value of the assets which were not declared. From the beginning, the tax form 720 - with its catalogue of fines and no statute of limitations on tax liability - was very controversial in Spain and at EU level.
The Court of Justice of the European Union (CJEU) ruled at the end of January 2022, that some of the obligations contained in this form are in breach of European laws. The ruling said that the fines for taxpayers as stated in the sanction regulations of Form 720, are excessive and violate the principle of the free movement of capital. In addition, failure to report assets results in undeclared income being taxed as unjustified capital gains, without the taxpayer being able to invoke the four year statute of limitations otherwise applicable in Spain. Finally, the CJEU states that the amount of the fines imposed is disproportionate to the sanctions generally provided for by the laws of Spain for similar infringements.
Tax form 720 has now been amended by Law 5/2022 in two key points: 1) The disproportionately high fines are eliminated. The previous sanction regulations, which provided for fixed fines for each violation and a penalty of up to 150%, are replaced by the regulations of the General Tax Code.2) The 720 tax model is now subject to the statute of limitations of general tax law, which means that any tax debts become barred by statute after four years. However, it should be noted that the duty of tax residents to report foreign assets abroad has been retained. The CJEU did not question the obligation to submit Form 720. The tax return for the previous year must be submitted by the end of March of the following year at the latest.
According to some tax advisors, a taxpayer who did not previously declare foreign assets due to the high fines, can do this now after the change of law. They need to file tax form 720 for the four previous years in addition to the current year. Since the CJEU ruling, taxpayers have been able to reclaim part of the fines that were un awfully paid in the past. If administrative proceedings are still ongoing, the fines can be challenged with reference to the CJEU ruling and taxes can be reclaimed if they are barred by the statute of limitations. With regard to proceedings that have already been completed, taxpayers can assert a claim for repayment via state liability ("responsabilidad patrimonial del estadolegislador").
Looking for a property in Ibiza or Formentera?
Let our AI assistant help you find your perfect property in Ibiza
Suggested Articles
1
 2
3
4
5
6
Legal & Real Estate
Hidden defects when buying a property in Ibiza
December 2025 – February 2026
·1967 views
Legal & Real Estate
Ibiza Becomes a Tax Haven for Gifts and Inheritances
October - December 2025
·1624 views
Legal & Real Estate
Pre-emption Rights in Real Estate Practice on Ibiza
August - October 2025
·1346 views
Legal & Real Estate
The Spanish Civil Law Procedures in the course of time
June - August 2025
·1400 views
Legal & Real Estate
New regulations for Holiday Rentals in Ibiza
April - June 2025
·4030 views
Legal & Real Estate
Does My Car with Foreign Plates Need to be Registered in ...
February - April 2025
·2503 views